Monday, May 23, 2022

Week 20: Momentum Analytics Portfolio update. Week ending May 20, 2022

The portfolio and indexes weekly return

The momentum portfolio outperformed the indexes this week too (but not in a good way*). The following is the weekly total returns for the portfolio compared to the index. As you can see my momentum portfolio lost money but much less than the broad market, So in one way the portfolio did outperform the indices. This is a very good sign, IMO since if the draw downs are less when the markets tank, it think the portfolio has done good job of risk mitigation. 


I am using Morningstar US market index as a benchmark. Thus the portfolio outperformed the market and beat it this week. 

Total Return: measures the theoretical performance of your holdings for a specified period of time, taking into account the beginning and end values of your investments as well as dividends.

Personal Return calculates the investor's returns, taking into account an additional factor in its calculation: the capital that you added or withdrew from your fund or portfolio throughout the specified period of time. The calculation of Personal Return illustrates how your allocation of capital has affected the performance of your portfolio. 

One of the things I have taken away from the last few months of tech/Nasdaq debacle is that there needs to be a risk system in addition to a reward system. The momentum portfolio automatically kicks in the risk mitigation when bullish momentum for stock is worsening and thus capping losses. 

This system worked beautifully well and this draw downs were capped in particularly volatile week.

Positions, Position Sizes and Momentum Updates

The only position that is still in green in AT&T (T), others are in red at the moment. 

Score classification

  • Score 0: Super bearish, no entry
  • Score 1: bearish, no entry
  • Score 2: Hold
  • Score 3: bullish, entry or hold
  • Score 4: bullish, entry or hold.

As it turns out the momentum scores can also assist with position sizing, with those that have the most favorable scores-setups have more additions to the positions making those portfolio positions heavier. 

Thanks for reading! Next post will be end of week 21, on or about May 28, 2022. Until then keep tracking the momentum!

Saturday, May 14, 2022

Week 19: Momentum Analytics Portfolio update. Week ending May 13, 2022

The portfolio and indexes weekly return

The momentum portfolio did as intended this week too. The following is the weekly total returns for the portfolio compared to the index. 


I am using Morningstar US market index as a benchmark. Thus the portfolio did better than the market and beat it this week.
 

Total Return: measures the theoretical performance of your holdings for a specified period of time, taking into account the beginning and end values of your investments as well as dividends.

Personal Return calculates the investor's returns, taking into account an additional factor in its calculation: the capital that you added or withdrew from your fund or portfolio throughout the specified period of time. The calculation of Personal Return illustrates how your allocation of capital has affected the performance of your portfolio. 

One of the things I have taken away from the last few months of tech/Nasdaq debacle is that there needs to be a risk system in addition to a reward system. The momentum portfolio automatically kicks in the risk mitigation when bullish momentum for stock is worsening and thus capping losses. At the same time, if the momentum turns bullish, one can continue to reap reward as long as the underlying market trends support the accumulation of the stock.

Positions and Position Sizes

Positions and sizes

Composition of portfolio

As you can see in the table below, the portfolio is heavily tilted towards consumer defensive and Industrials compared to the SP500. Thus the portfolio is adapting to the prevailing trends in the stock market by weeding out those that are not in favor (technology, financials). I do not invest in health care stocks so it will always be 0 and I think that the energy sector is a little overextended so I have not invested in it these past weeks.


Score classification

  • Score 0: Super bearish, no entry
  • Score 1: bearish, no entry
  • Score 2: Hold
  • Score 3: bullish, entry or hold
  • Score 4: bullish, entry or hold.

Momentum updates of stocks in portfolio 

Stocks and their momentum scores at end of the week.

As it turns out the momentum scores can also assist with position sizing, with those that have the most favorable scores-setups have more additions to the positions making those portfolio positions heavier. 

I fixed the issue with the 4th indicator which was giving me some whipsawing - after using MFI derivative, ADX derivative, RRG momentum derivative, I think I have found one to help with clearer signals - Aroon derivative. This is important since I want the indicators to overlap but not have a correlation of 1. Aroon derivative is unique as it is in effect "time over price signal" as opposed to "price signal over time".

Thanks for reading! Next post will be end of week 20, on or about May 21, 2022. Until then keep tracking the momentum!

Saturday, May 7, 2022

Week 18: Momentum Analytics Portfolio update. Week ending May 6, 2022

The portfolio and indexes weekly return

The momentum portfolio did as intended this week. The following is the weekly total returns for the portfolio compared to the indexes 

  • Dow Jones 30 (DIA) was -0.50%
  • Morningstar US market index -0.57%
  • Momentum Analytics Portfolio: -0.72%
  • SP500 Index (SPY) was -0.76%
  • Total US market for the week (VTI) was -1.19%
  • Nasdaq100 (QQQ) was -2.90%
Thus the portfolio did better than SP500 and total market (US) but Dow30 index did better this week than all other benchmarks

Results by month since start of momentum investing

Here are the monthly results (to date) of the portfolio compared to Morningstar Total US Market index as benchmark

Month             total return                personal return             index return 

Mar                 3.72%                         2.68%                             3.67%

Apr                 0.55%                         -1.85%                            -9.09%

May (to date)    -0.72%                       -0.75%                            -0.57%

I use Morningstar to track my portfolio returns. According to Morningstar,

Total Return Total Return measures the theoretical performance of your holdings for a specified period of time, taking into account the beginning and end values of your investments as well as dividends. 

Personal Return Personal Return calculates the investor's returns, taking into account an additional factor in its calculation: the capital that you added or withdrew from your fund or portfolio throughout the specified period of time. The calculation of Personal Return illustrates how your allocation of capital has affected the performance of your portfolio. 

As seen in the returns comparison, the momentum portfolio has done well compared to the total US market index.

Momentum Portfolio return (Bold green line), Morningstar US Market Index (Light Grey). Courtesy Morningstar.com

 Positions and Positions sizes

Positions and their proportion

Buys/Adds this week

HON - Honeywell
TGT - Target
AIG - American International group
CAT - Caterpillar
GD - General Dynamics Corp.
LMT - Lockheed Martin
MMM - 3M Co.
DOW - Dow Chemicals
MA -  Mastercard
DUK - Duke Energy
IBM - International Business Machines


Sells this week

RTX - Raytheon
PG - Proctor and Gamble


Score classification

  • Score 0: Super bearish, no entry
  • Score 1: bearish, no entry
  • Score 2: Hold
  • Score 3: bullish, entry or hold
  • Score 4: bullish, entry or hold.


Momentum Updates of the Stocks in Portfolio.

TICKER/ Score/ Vector/ % Profit/Loss of position
AMT/ 3/ Declining/-7.43%
MA/ 2/ Declining/-4.26%
WMT/ 4/ Ascending/-4.93%
CAT/ 3/ Ascending/-2.56%
PEP/ 2/ Ascending/-2.32%
MMM/ 2/ Ascending/-1.72%
AIG/ 1/ Ascending/-1.53%
HON/ 4/ Ascending/-1.16%
TMUS/ 4/ Descending/-0.71%
KHC/ 4/ Ascending/0.39%
DUK/ 4/ Ascending/1.08%
LMT/ 4/ Ascending/0.95%
IBM/ 4/ Ascending/1.42%
T/ 4/ Ascending/3.72%
TGT/ 3/ Descending/-6.09%
GD/ 3/ Ascending/-0.98%
DOW/ 3/ Descending/-0.97%
CL/ 3/ Ascending/-4.34%
WM/ 3/ Ascending/3.44%

There is one small issue I noticed with my method. As you can see I bought AIG this past week but by Friday the momentum score of AIG was down to 1 which triggers the sell rule. In order to reduce whipsaws, I purposely set the time frame to be medium long of 60 days, which covers 2 months. This got me thinking, of substituting the ADX indicator with RRG momentum indicator ROC. Thus I will pick those stocks whose momentum vector is improving w.r.t other stocks in the group. I am using the SP100 index ETF OEF as control for the group. Hopefully this will reduce the short in-out trades which I do not want to engage in.

Thanks for reading!

Next post will be end of week 19, on or about May 14, 2022. Until then keep tracking the momentum!


Sunday, May 1, 2022

Momentum Analytics Portfolio update end of week ending April 29,2022

This week was miserable in the equities market. I feel that the momentum portfolio did just as well (or badly) or better (less poorly) than broad markets. But what a fricking sell off. Year to date, SPY (SP500) is down 12.99%, QQQ which tracks Nasdaq is down 21.17% and DIA which tracks the DOW 30 index is down 8.81%. This is perhaps the first clue into what markets have better momentum versus which sectors are doing poorly. 

Results by month since start of momentum investing

Here are the month-to-month results of the portfolio 

Month             total return                personal return             index return 

Mar                 3.72%                         2.68%                             3.67%

Apr                 0.55%                         -1.85%                            -9.09%

I use Morningstar to track my portfolio returns. According to Morningstar,

Total Return Total Return measures the theoretical performance of your holdings for a specified period of time, taking into account the beginning and end values of your investments as well as dividends. 

Personal Return Personal Return calculates the investor's returns, taking into account an additional factor in its calculation: the capital that you added or withdrew from your fund or portfolio throughout the specified period of time. The calculation of Personal Return illustrates how your allocation of capital has affected the performance of your portfolio. 

As seen in the returns comparison, the momentum portfolio has done well this week compared to the total US market index.

Positions and Positions Sizes

This bring us to the positions in my portfolio.

Momentum Analytics portfolio positions

The positions are their momentum scores are reported below

Name (Ticker, Composite momentum score)

1) American Tower Corp. (AMT, 2): AMT belongs to the real estate sector and specialty REIT industry. The specialty REIT industry is doing well this may provide the tailwinds that the company needs to sustain the long position. The Composite momentum score has been generally in the bullish zone since April 1st but tipped into the score 2 after the market meltdown on Friday. The price action has not been keeping up with the bullishness and I hope this represents a pullback and that the price will bounce back.

2) AT& T Inc (T, 4): T belongs to the communication services sector and Fixed telecommunications industry. The Fixed telecommunications industry is doing well recently April 21, 2022 and this may provide the tail winds for the company.  The Composite momentum score has been overall bullish since April 8th, 2022 the price action has been tracking sideways and hopefully indicates accumulation and further price increase.

3) Colgate-Palmolive Co (CL, 3): CL belongs to the consumer staples sector and personal products industry. The personal products industry is doing better than the average market this may provide the tailwinds for the company.  The Composite momentum score has been bullish recently but has dipped into the HOLD (2) category since the market drop this Friday. Hopefully, this represents, resistance to further drop and the momentum is able to bring price back into the favorable position. If score falls further, it will trigger the sell rule.

4) Dow Inc (DOW, 3): DOW belongs to the Materials sector and Commodity chemicals industry. The commodity chemicals industry is doing well since April 7 and this may provide the tailwinds for the company.  The Composite momentum score has been bullish since January 13, 2022.  The price action has been keeping up with the bullishness and I hope the recent drop represents a minor pullback

5) General Dynamics Corp (GD, 3): GD belongs to the Industrial sector and defense industry. The defense industry is doing well since January 14th and this may provide the tailwinds for the company. The Ukraine-Russia war is clear factor in the surging of the defense industry. The Composite momentum score has been bullish since January 13th, 2022. The price action has been keeping up with the bullishness and I hope the recent drop represents a minor pullback. 

6) International Business Machines Corp (IBM, 3): IBM belongs to the Technology sector and computer services industry. The computer services industry is doing poorly overall but perhaps a small blip of improvement as of April 22nd, 2022. The Composite momentum score has been bullish only recently since April 20th, 2022. I anticipate this may fall back to HOLD category, then if the momentum were to continue, would take up again from there. 

7) PepsiCo Inc (PEP, 2): PEP belongs to the consumer staples sector and soft drinks industry. The soft drinks industry is doing really well  since January 3, 2022. The Composite momentum score has been bullish  since April 20th, 2022 but fell to HOLD on last Friday.

8) Procter & Gamble Co (PG, 2): PG belongs to consumer staples, personal products industry. This industry has been only recently since April 22 doing better than its performance compared to the total market. Also PG is one of few on this list that has moved up in ranks from a bearish category to HOLD and then briefly a bullish score of 3, early part of last week. Friday sell off in the general market put it back into the HOLD but on the long side. 

9) Raytheon Technologies Corp (RTX, 3): RTX belongs to Industrial sector, Aerospace industry. This industry as a whole as weakening momentum compared to its performance w.r.t total market. The ticker has been bullish since February 2 but I need to keep a close eye on this one. I am afraid the slowing momentum and weakening industry performance may trigger a sell signal, but lets see what the rules have to say when the time comes.

10) Target Corp (TGT, 3): TGT is in the consumer discretionary sector, broad line retailers industry. This industry has had a weak performance compared to the broader market indexes. The ticker went bullish on April 8 but fell to a 3 category after the broad market sell off on 4/29/2022. 

11) The Kraft Heinz Co (KHC, 4): KHC belongs to consumer staples sector, food products industry. The stock price has had a robust momentum since February 15. Currently still at a score of 4 even with the market sell-off, has a ADX suggesting trending strength and tailwinds with industry performance, this stock has high chance of pulling back and stock price increase again. 

12) T-Mobile US Inc (TMUS, 3): TMUS belongs to communication services sector, mobile communications industry. It was doing well with a momentum score of 4, until the Friday sell-off where the momentum score fell to 3, still a bullish score. It turned bullish on February 3 and continues to range in the bullish score trend. The mobile telecommunications industry performance however, if weakening.

13) Walmart Inc (WMT, 4): WMT turned to a bullish momentum score on March 7th and has been strong bullish since. The momentum is strong and hopefully reflects a minor pullback w.r.t last Fridays price action and recovery in next few days. 


14) Waste Management Inc (WM, 4): WM belongs to industrial sector and waste and disposal industry. The scores turned to bullish on April 4 and continue to maintain a strong momentum.

Score classification

Score 0: Super bearish, no entry

Score 1: bearish, no entry

Score 2: if improving, not buying yet - "watchful for short reversal", if falling, not selling yet - "watch for long reversal"

Score 3: bullish, entry or hold

Score 4: bullish, entry or hold.

Sells

This week I sold TSLA at a small loss. Its score dropped from a 3 to 1 and I sold it for a 2.2% loss. 

Adds

This week I added GD, IBM, PEP, PG this week. CL is one I am watching closely, based on momentum score it is not yet time to sell but if it falls to 2 then I will sell it. At present all the positions are at a loss as reported below

Individual Stock Performance

Name (ticker, unrealized gain/loss)

American Tower Corp. (AMT, -8.59%)
AT&T Inc (T, -0.56%)
Colgate-Palmolive Co (CL, -4.08%)
Dow Inc (DOW, -2.7%)
General Dynamics Corp (GD, -2.04%)
International Business Machines Corp (IBM, -2.59%)
PepsiCo Inc (PEP, -1.58%)
Procter & Gamble Co (PG, -0.67%)
Raytheon Technologies Corp (RTX, -5.6%)
Target Corp (TGT, -5.96%)
The Kraft Heinz Co (KHC, 4)
T-Mobile US Inc (TMUS, -3.58%)
Walmart Inc (WMT, -2.75%)
Waste Management Inc (WM, +5.15%)

Next update 5/8/2022, until then keep tracking the momentum.

Wednesday, April 27, 2022

FAANG-M stocks, how they stack up: A momentum analytics study

Introduction

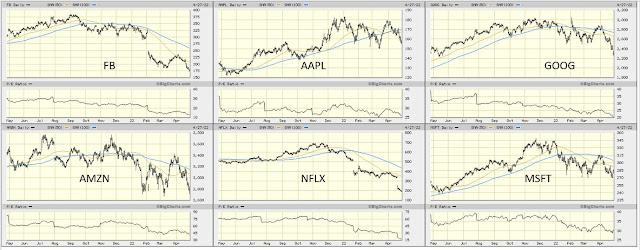
The five stocks that make up the FAANG-M are facebook/Meta (FB), Amazon (AMZN), Apple (AAPL), Netflix (NFLX), Alphabet (GOOG) and Microsoft (MSFT).

As of the time of writing this note, the SP500 is heavily tilted to these mega caps. Apple Inc  makes up 5.90% of the SP500 index, Microsoft Corp (5.60%), Amazon.com Inc (4.05%), Facebook Inc A (2.29%), Alphabet Inc/Google is 3.98% (between A and C class shares) 

Thus stock price changes in these companies can have a significant impact on the price of general market indexes. 

The price chart of the tickers in question is shown below (charts courtesy bigcharts.com). If you are familiar with the background you can skip the next few sections and go straight to the tabulated results. 

1 YEAR STOCK PRICE

Background

Price momentum is an observed tendency for a rising price of an asset to keep rising, and a falling price to keep falling. 

Thus stocks with strong performance tend to continue outperforming for the next set period. The period is important since a stock that is ripping today may not do so in 5 years. The effect of momentum is is best seen in the short and mid-term time frames. 

A little background on this concept is pinned as a tweet in my profile. 

https://pbs.twimg.com/media/FRKEZr9X0AMH4Py?format=png&name=small

Using a composite score derived from momentum indicators, I have set up rules based entry and exit signals. These allow me to buy and sell without much emotional wrangling. If the rule is met - buy, if the rule holds - hold and if the rule is broken - sell.

Vector direction and strength: 

Just as a vector (in physics) has direction and strength, the price movement has direction and strength. 

Based on the 4 medium term indicators for direction of the price movement (bullish versus bearish) and 1 indicator for the strength of the price movement, I am able to break down price action of any stock to one of 5 grades or scores.

Score 0: Highly bearish
Score 1: Bearish
Score 2: Neither bullish nor bearish
Score 3: Bullish
Score 4: Strongly bullish

Score of 0 and 4 have the added caveat of watching for reversals as with any extreme price movements. With this basic information lets analyze the momentum for the 6 stocks in question

The Indicators:

As a gauge of direction (bullish or bearish), I am using a 60 day period RSI (relative strength Index), MACD (Moving averages convergence divergence), MFI (Money flow index) and Rate of change (ROC). As a gauge of strength I am using a 14 day ADX (average directional index) but, I do not incorporate it in the calculation of the score. The ADX is only to inform if there is going to be strong up or down movement possible or if the price is going to slowly trend sideways

RSI and ROC are pure price momentum indicators, one is range bound (0-100) and other is not. MFI is a price and volume momentum indicator which is also range bound. MACD is both leading and lagging indicator based on price. Thus, it is expected that the 4 indicators would provide a different input and it is important that they NOT have a correlation of 1. 

Application of rules

When the momentum score is 0 of 1, it not an ideal time to add or initiate a position. When the score improves to 2, the ticker could be on a watch list and a good entry point is when score improves to 3 or 4. As long as the price stays 3 or 4, one could hold the position When the price momentum slows to bearish and falls to 1 or 0, sell signal comes on.

Results

Thus as of today, none of the megacaps are showing a buy signal. Amazon is on watch and faring better than the rest.

Saturday, November 27, 2021

A Concept Network Analysis Of Upstart Holdings Inc. - Connecting The Dots


Summary

  • Here in is presented a novel method to analyze underlying business to understand connections, synergies, scale, shared strategic resources & inter-dependencies that may make UPST a stellar company.
  • This type of analysis is complementary to the conventional methods of fundamental or technical analysis, and lets semantic data reveal the patterns and relationships. Connect the dots.
  • Based on my concept analysis, Upstart Inc is a disruptor, filling an unmet need. It has the vision and an operating mechanism for growth.
Small Network of Pins

anilakkus/E+ via Getty Images

A deep dive into Upstart Holdings Inc. (Ticker: UPST). Network analysis of concepts fiscal quarter end June 2021.

Introduction

There are many services that provide stock or company analysis, those analysts choose either fundamental data (numbers like profit, loss, revenue etc.) or technical analysis (stock price action) which are important for evaluation of the company. This article is not it.

This article presents a method to understand the underlying business and to get a sense of connections, synergies, scale, interconnections, shared strategic resources and inter-dependencies that make a company successful.

Background

In graph theory, a graph (network) is a structure containing a set of objects in which the objects are in some sense “related”. The objects can be ideas, concepts, discrete elements. I use visual and network analysis in medicine and biology to analyze relationships between proteins, genes, diseases etc. I am applying similar principles to do deep dives of companies to analyze companies to invest in.

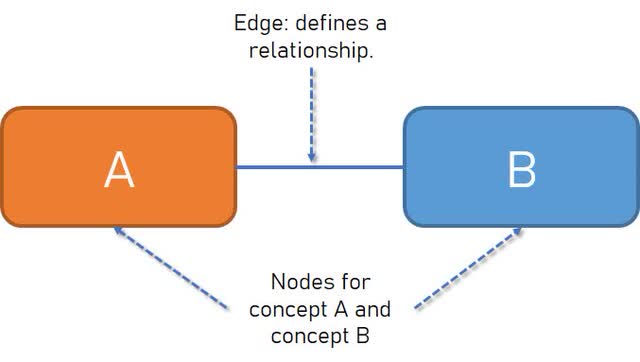
A network graph is made of nodes and connections (edges). Each node is a tangible concept or entity. Lines connecting the nodes are relationships between any two entities are called edges. Thus, if 2 entities are related, there is a line (edge) connecting 2 nodes. In the most reductive sense, this is represented in the figure 1, with 2 nodes and 1 edge. This type graph is an excellent tool to represent relationships between 2 ‘concepts’.

simple network

Figure 1: A simple network, concept nodes (A and B) connected by an edge relation

veuepoint (self)

These graphs are a non-random mathematical models of relationships. This process is unsupervised (no human bias) and lets the data reveal the patterns and relationships , allowing confirmation of the known and to reveal the unknown.

Such tools can help increase understanding and reading between the lines. In my opinion, this type of analysis is crucial but severely lacking. Intangibles like company work culture, mission, flywheels, synergies, leadership can be “discovered” by such tools. With this background, lets analyze the concepts presented in the conference call for fiscal quarter ending June 2021 (UPST)

Unsupervised concept network analysis of Upstart and its AI platform

A network map of Upstart Inc

Figure 2: The entire unsupervised network of concepts related to Upstart AI platform

Veuepoint (self)

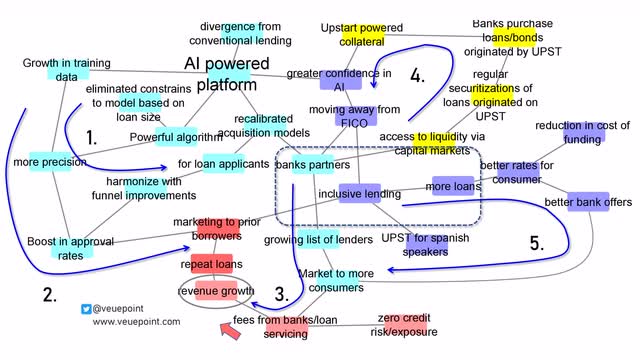
The above figure is busy so let me break it down into ‘smaller models’ which lets us look at it in detail.

Concept mapping of Upstarts AI platform

Figure 2A: Upstart AI platform concept analysis closer look at concepts 1, 2 and 3

Veuepoint.com (self)

1) A platform (and the business) which gets better over time.

This section of the network model shows the amazing internal flywheels that are synergistic to the workings of Upstart. Lets begin with our attention to the left of the figure (blue arrow #1). This section describes the AI platform and the developments that upstart has implemented for it. The AI platform is a self learning entity, the more data it processes the better it gets at making decisions. This growth in training data leads to more precision and then in turn leads to a boost in approval rates for applicants. This leads to more loans being approved which in turn leads to refinement of the algorithm. Thus one can envision, this process to get better and better over time, and be able to identify those applicants which are loan worthy but missed by other scores (Like FICO).

2) Revenue growth multipliers

The next concept that is evident from the network map is shown by blue arrow #2. Here the improvement in AI algorithm, translates to revenue growth. This is achieved by the intermediary steps of increased precision, leading to boost in approval rates, leading to approving more borrowers. The company also has stated emphasis on marketing to prior borrowers. This is an excellent strategy since they have already qualified by upstarts AI and have demonstrated the ability to pay back the loans. These repeat loaners add to revenue growth.

3) Increase in lenders adds to borrower related revenue growth

The third network concept is highlighted by blue arrow #3. This revenue growth is not only being increased by growth in first time and repeat loan applicants, it is also growing as the number of lenders increases. This allows the banks to market to more consumers and this provides fees from banks for loan servicing (Blue arrow #3). The important aspect of this revenue stream is that Upstart is able to achieve this growth with zero credit risk or exposure. This is borne by banks and not by Upstart.

Concepts 4 and 5, central tenet

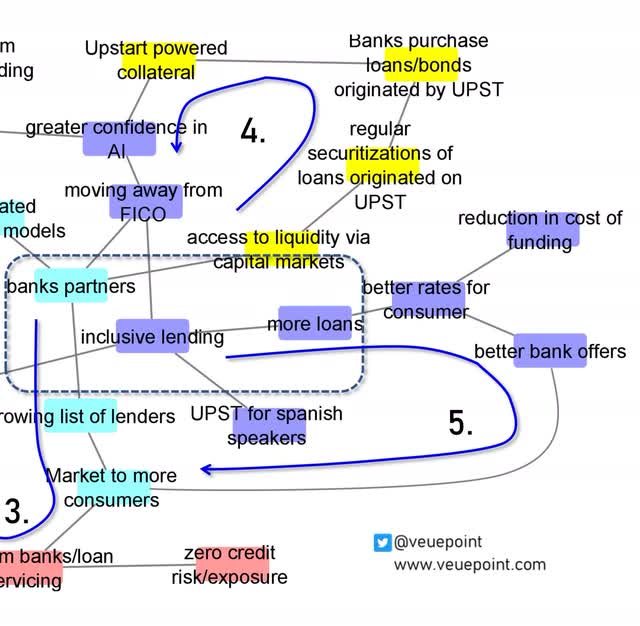
Figure 2B: Upstart AI platform concept analysis closer look at concepts 4 and 5

Veuepoint.com (Self)

4) Upstart powers collateral that partner banks can use

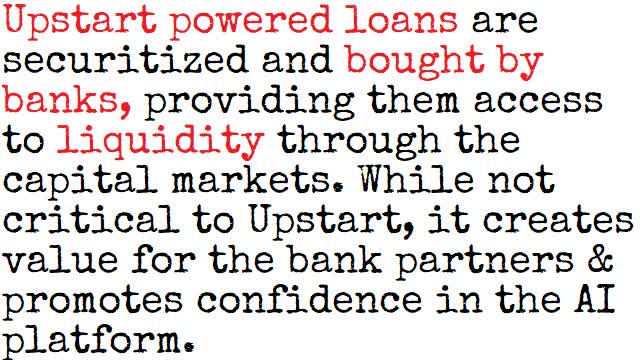
The fourth segment of this network is the part in yellow on top right and is an interesting one. Upstart is able to provide access to liquidity to banks by exposure to capital markets. The loans that originate at Upstart can be “securitized” and sold to banks that are willing to buy them. This upstart “powered” collateral that banks have (bonds, loans), allows banks access to more liquidity and capital.

Upstart powered loans provide access to capital markets

Concept card 1: liquidity and access to capital markets

Veuepoint.com (self)

This is not necessary for working of upstart but provides an excellent service and value to the partner banks. This increases the working relationship that banks have with Upstart. This also has another benefit, as banks work with this upstart originated collateral, they are also demonstrating greater confidence in AI platform and this has lead to some banks discontinuing legacy scoring systems like FICO altogether. That is an exceptionally disruptive nature of the this arrangement.

5) "Inclusivity" revealed as the central tenet

The last segment of the network are the purple nodes on the right, this deals with the nature of the platform and its goal of inclusivity. As more loans are offered, upstart and bank partners are able to offer better rates to the consumer, leading to better offers from the bank and overall reduction in cost of funding the loan. This is a virtuous cycle which keeps working to improve at each iteration, lend more, to more eligible applicants and have them and banks get a better deal out of the transaction.

The network began with AI powered platform as the starting node. However, when all the concepts were linked and connected, the central nodes that seem to be the crux of the graph are bank partners – inclusive lending – more loans. This tenet is central to the working of the company and the network map generated by unsupervised non-random modeling was able to pin it down to this. Their mission to enable effortless credit based on true risk is acted on by a culture of “inclusive lending”.

Their modus operandi is exemplified by their mission statement “to enable effortless credit based on true risk. We are a leading artificial intelligence (NYSE:AI) lending platform designed to improve access to affordable credit while reducing the risk and costs of lending for our bank partners. Our platform uses sophisticated machine learning models to more accurately identify risk and approve more applicants than traditional, credit-score based lending models.”

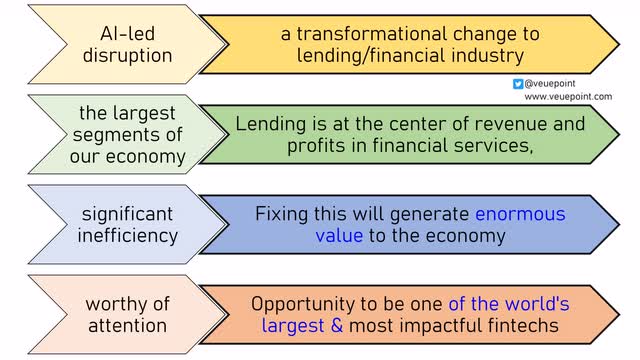
Key drivers of Upstart philosophy

Concept card 2: Upstart Key drivers and consequences

Veuepoint.com (self)

As seen in the figure above, the key concepts that drive Upstart have huge consequences. Lending is the center of revenue and profits in financial services. This is one of the largest segments of the economy. However, lending is fraught with inefficiencies. Artificial intelligence can assist in eliminating these inefficiencies. This can generate enormous value to the economy. AI powered lending could be the most transformational change for this industry and provides Upstart the opportunity to become one of the world’s largest and most impactful fintechs in the years to come.

But wait there is more..

Upstart auto lending could be the new hyper-growth venture.

Autolending is six time bigger than personal loans

Concept card 3: Autolending is larger than Personal loans

Veuepoint.com (Self)

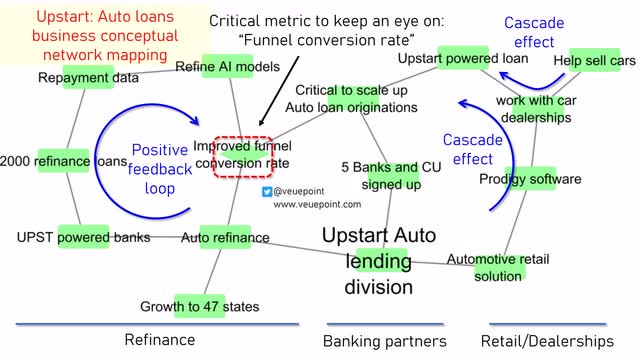
Upstart (UPST) recognizes the potential for growth in a related business by applying similar principles as personal loans to car loans. The figure below shows network model of concepts for auto lending. I will discuss key themes that stood out.

Autolending unsupervised network of concepts

Figure 3: Auto lending segment and Upstart concept network mapping

Veuepoint.com (Self)

A positive feed back loop

The auto refinance sector, via upstart powered banks offer loans to applicants. This is also based off their Artificial intelligence algorithm which makes a determination of eligibility just as it does in the personal loans space. As of their earnings update in August 2021, they had 2000 loans. The repayment data from these loans is utilized to refine the AI models, which can then in turn improve the funnel conversion rate. This is the rate of applicants who are approved for a loan over total number of applicants.

The company will continue to do exceptionally well, provided the percentage of applicants who are approved compared to the total applicants continues to grow. This will in turn increase the data of loan applicants, repayment data and further refine the AI to improve the detection on ideal applicants. This is noted as a “positive feedback loop” or a “flywheel effect”, similar to what was seen in the personal loans space. The best thing about this, is that the system keeps learning over time to better itself and make decisions with even better accuracy. The funnel conversion rate (noted as a diamond node) is a critical lynch pin in this network graph, since the positive loop is sustained only if the funnel conversion rate is positive and keeps improving.

A cascade effect of Prodigy, car dealerships and car loans

The second section of their auto lending concept map is the effect of Prodigy and its association with car dealerships (shown on right hand side of figure 4). Prodigy works with car dealerships to assist these businesses sell cars. It claims to streamline the process of car selling. The synergistic benefit of prodigy working with dealers to sell more cars is brought forth when a portion of these cars sold will also be financed through a upstart powered loan. The more cars prodigy helps sell, the more loans upstart can provide using its algorithm. This aspect of upstart is nascent and will continue to grow as more and more banks and credit unions sign up.

Overall, the concept maps exhibits good internal synergies and are sentiment positive.

A note on the work place philosophy at Upstart as a company.

Upstart is moving to a “digital-first model”, where most employees can live and work anywhere in the U.S. Besides the usual reasons for why hybrid or work from home has advantages for a place like Upstart, I would like to highlight a statement which is quite powerful as to the vision of what this company plans to do. “Given the scale of our ambitions and the talent we need to aggressively pursue our goals, we need to tap into talent across the entire country”

Digital first model of Upstart allows work from home

Concept card 4: Upstart and digital first model

Veuepoint.com (Self)

Conclusions

The semantic/concept network mapping has revealed several unique strengths and none critical deficiencies

Actionable considerations

The above article is not financial or investment advice. It is sharing my method of evaluating companies. I have worked with network graphs for more than a decade with applications to other field, this is the first foray to publish its application to company analysis formally. Comments and feed back are welcome.

Based on my concept analysis, Upstart Inc is a disruptor, filling an unmet need. It has the vision and an operating mechanism for growth. I am invested in Upstart. The company narrative is exceptional and as long as this narrative continues, I will stay invested.


Disclosure: I/we have a beneficial long position in the shares of UPST either through stock ownership, options, or other derivatives.

I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article

Sunday, September 26, 2021

Peloton (PTON): a comparative analysis of visitors to its website and competitors

This brief article looks at comparative web traffic to onepeloton.com, which is Peloton's homepage and the websites of its closest competitors.

Method: 

I chose Nordictrack, Myxfitness and Echelon as 3 closest competitors to Peloton, since they also provide hardware (exercise bikes, treadmills) and some form of subscription service. This study was performed to look at trends in website visitors to the respective home pages from around the world and see if there would be any insight gained. Data was complied from Cloudflare.com radar tool with a look back period of 30 days. 

Figure: Comparison of visitor location to website by country (Y-axis represents percentage)

Results: 

  1. The 4 companies were tied very close to each other for visitors origination in US. 
  2. Countries where Onepeloton.com was a leader were with visitors from Germany, Ireland and Sweden. Besides these three, it was not a leader in any of the other top countries studied. 
  3. Myxfitness.com was a leader for visitors from UK, Australia, the Netherlands, Japan and Georgia.
  4. Nordictrack was a leader for visitors from France, Singapore, India, and Hong Kong and seemed to have good penetration in Asia.
  5. Echelonfit.com was the leader when it came to visitors from Canada, Brazil, Poland, Colombia, Portugal and Austria. It had a the biggest share in South America.

Discussion

There did not seem much headroom for any of the companies when it came to website traffic for US. All of these had highest traffic percentage from US and it was close. The differences were most apparent when we looked at visitors from other countries. Australia which was recently opened up as a market for Peloton lagged behind Myxfitness and Nordictrack in this study. Echelonfit seemed to have a greater brand awareness and penetration in South America where it topped in both Brazil and Colombia.It was also the one with a dedicated .MX site. Nordic track had the greatest brand awareness in Asia, as suggested from highest percentage of visitors from Singapore, India and Hong Hong. Myxfitness led for visitors from Japan. There are some limitations to this study, most notable, the look back period is 1 month, second, website visitors does not always translate into customers but at least a small fraction of people visiting the website could be come potential customers for the services. Finally, VPN and proxy tools could affect the origination of web traffic but I would anticipate this would affect all the websites proportionally and this would be a minor issue for comparison. 

Disclaimer: I own shares of Peloton. As part of being a good investor, it is important to carefully evaluate investments from time to time. This is to assess if the companies you are invested continue to meet your expectations.


Saturday, September 25, 2021

Demystifying Palantir (PLTR) for a new investor

Background:

This article is an attempt to breakdown what Palantir does in a simple easy to understand manner. This article is not going to discuss the financial metrics or valuation of the company which is discussed here (Palantir Operating profitability and expense trends). I have also reviewed the numerous contracts that Palantir has won (as of Sept '21) since they became public. This article can be accessed here (A network of Palantir contracts). This piece is more about what it does in a hopefully simple to understand manner.

The word Palantir refers to a fictional magical artifact. J. R. R. Tolkien (of Lord of the Rings fame) imagined this to be an indestructible crystal sphere. Main use for this object was for communication and to see events in other parts of world (past or future). The name of Palantir Technologies is apt in its description of it capabilities. The ability to see what other can't see. 

So lets dig into what some of Palantir Technology does.

In its most basic function, 

Palantir's programs use computers and software to analyze information, identify and learn from the problem and devise solutions.

Palantir does some of this in part by collecting data from multiple sources, cleaning and making it usable, comparable. Finding patterns using visualization techniques. Then using the information using human intelligence or Machine learning (ML)/Artificial intelligence (AI) to solve the problem.

1) Helps with Data integration and  translation.

Palantir helps organizations to build a solid, high quality database from different sources. Palantir will translate the integrated data interactions in easy to read format. This of course comes with high degree of customization.

2) Helps with Data interconnections.

Data is often spread across the enterprise. Models derived from these disconnected data are difficult to comprehend. 'Micro Models' is a new approach developed by Palantir to address this problem. Micro Models addresses parts of a large problems. It then combines those solved parts back for a solution. Thus, it breaks a ‘BIG’ problem into smaller problems and solves all the smaller problems. Palantir software then chains those solutions together, to solve, the ‘BIG’ problem. The standardized solutions chain thus leads to interconnected workflows. 

3) Helps to Model Objectives.

Business objectives are clear targets and goals for a company to achieve. They may also include strategies achieve the said tasks.

Figure: Palantir keeps improving on the processes leading to objectives being met and improved

The objective model (OM) collects goals, training, evaluation data, result and metrics. This is in context of the underlying logic behind the objective. Thus, OM is a hub, receiving, transmitting and analyzing information about goal achievement. As  with micro-models, Palantir binds individual models to a larger design. This design powers several different workflows. The design has a 'write back' property to improve accuracy of future uses.  Thus, Palantir keeps refining the process, to ensure goal accomplishment and goal improvement.

4) Capable of building and deploying AI/ML Infrastructure

Palantir combines the data foundation (#1) with end-to-end AI/ML deployment infrastructure.  Think of these a AI/ML codes 'widgets' (each doing a specific task), placed at various points in a task workflow. Palantir allows scientists to decide where to place them. They also know how the widgets interact and check their function.  

5) Provides Artificial intelligence for Internet of Things and Edge computing.

Many electronic devices a.k.a 'things' use internet to stay connected  (e.g a smart thermostat, TV etc)  . This internet 'of things' (edge) usually communicates with a Cloud computing (center). Decisions go back to the IoT devices. This can be slow.  Palantir's 'Edge AI' powers decision at the edge detaching the cloud. Thus processing data is faster, with minimal lag, for immediate use. This Palantir tech is being used in ground vehicles, watercraft and spacecraft.

Applications:

The applications of such a technology are rather unlimited. Think of Palantir like a Swiss army knife a multipurpose tool for any number of applications.  I have highlighted some of the applications below

1) Solving financial crimes

Financial crime is complex. There are many moving parts, including the bad actors who are responsible for the crime. Also involved are intermediaries (banks/financial institutions) and victims (individuals and companies).   Criminals are also using newer and smarter ways to commit crimes. Hackers have held companies at ransom demanding cryptocurrencies. These innumerable data points make it difficult to track a financial crime. Conventional approach has been a 'fixed set' of rules with one lead leading to next, which leads to the next. This is labor and time intensive. Palantir provides tools to join billions of records to analyze data fast. Palantir’s enables linking of customers, networks, and counter parties. All this is compliant with privacy and security standards per Palantir. This system can allow banks to move away from the legacy systems. Palantir guides analysts through the investigation to focus on the most important risks. With this high level 30,000 foot view analysts can multitask the investigation. The analyst can addend the generated report to be filed with the authorities.

2) In automotive industry and racing

Palantir is working on its data analytics with Ferrari the car company. The vast number of data points are being used to make the cars safer, faster.

3) Use in Data protection

While data is being used for analysis, Palantir ensures that the data is secure. This is per the regulations that govern data privacy. This compliance with regulatory bodies allows continued use of data in correct manner.

4) Use in Defense and military applications

Palantir has worked for a long time with US armed forces. Its use is in principle the same.  Palantir integrates data external sensors/sources through a single point of access. This reveals unseen links across their entire universe of data. Palantir use if in Data Integration, Resource Planning, Finance & Accounting and Military Readiness.

5) Applications also include using Palantir software in energy sector.  

Energy companies deal with fluctuations in energy demand, transition to green energy. Palantir assists with these concerns by digitizing data and using it analytics.

6) Use in financial planning and analysis

Palantir queries, unifies, creates a usable database for financial management

Palantir has been used for analyzing troves of financial data to streamline expenses, budgets etc. It can query multiple disconnected systems for data, unify it into one harmonized database. This then lets it create a foundation database that finance professionals can use to analyze portfolio, audit finances, track budgets, reprogram funds and reallocate capital. This has been successfully applied to study contract renewals in US army.


7) Use in health sciences and medicine


Figure: How Palantir can transform medical discovery. The platform is flexible enough to be positioned at every sequential step of medical scientific process, enhancing efficiency and speed.

Palantir's foundry is a powerful tool that is being used currently for all aspects of medical progress. From basic sciences, pre-clinical studies including drug design and development, to developing cell clones Foundry can assist with data management. It also accelerates medical discovery by assisting in phase 0, I, II, III and IV clinical trials. Finally, data can be analyzed from post marketing information making Foundry indispensable for medical discovery. 

Conclusion:

Palantir's software (called Foundry & Gotham)  is a versatile tool which can be used in any industry, seeking solutions to problems which had previously been difficult problems to solve. The program does this by its unique approach of visualizing and finding patterns in data allowing either machines or humans to interact with the patterns for finding solutions. The sheer versatility and application is evidenced by its numerous contracts it has with industry in variety of sectors. 

Disclaimer: I own shares of Palantir. Information has been sourced from public websites.


Sunday, September 19, 2021

Global-E (GLBE) has an amazing mechanism to succeed

If you want to know what is to follow without reading  further, it is this: Global-E (GLBE) has an amazing mechanism to succeed. I am glad I own shares of this company. 

I was most interested in how the company works and how it is going to keep the flywheel(s) spinning. Using the information present in form F1 that was filed with SEC by the company (Sep-07-2021), I generated a unsupervised semantic network model. The figure is shown below,

Figure 1: An unsupervised network analysis of Global-E (GLBE) business overview based on SEC F-1 filing data

Figure legend:

  1. Merchant side concepts are shown as green nodes to the left
  2. Shopper side concepts are shown in pink nodes on right.'
  3. The edges, (lines) connecting the nodes are relations that were abstracted from the SEC filing.

Comments:
1. GLBE has plenty to offer the merchants (green square shape on left), which makes it attractive for a merchant to sell on their platform. Success of the merchant is in turn a measure of success of GLBE
2. GLBE also makes it extremely easy for shoppers to buy (Pink square shape on right) across boundaries with all the facilities it has to offer (see figure 1, pink nodes in capital letters as well as figure 2 below, this is from their F-1 filing)

Figure 2: From Global-E F1 filing with SEC Sept 2021

MOST IMPORTANTLY, 

Two Key observations are revealed in the network figure (this is why I love this type of modeling, it allows to read between the lines).

  • Observation #1: Offloading complexities occupies a central role in the workings of this set up. This is the central tenet of Global-E's workings and this is the lynch pin around which their success rests. And they are doing a great job at it. 
  • Observation #2: The interface between merchant and shopper is right at the payments, pricing and duties/taxes nodes. The alignment of this interface (payments, pricing, duties/taxes), is the crucial solution of cross border commerce. This is the under pinning platform for the 'off loading of complexities' central node.

This is a fantastic network model, that the computational network algorithm has generated. This is purely based on textual and conceptual information in the filing. I am amazed at the sheer simplicity and extreme robustness of the the model which reflects the values of the company. I am pleased I am invested in the company and would not mind adding more soon!

Disclaimer: I own shares of GLBE. Data obtained from F1 filing, SEC and public sources.

Mercadolibre (MELI), a digital footprint more than just Latin America (LATAM)

I was wondering about the reach of some of the continent specific e-commerce platforms. For example, Mercado Libre (ticker: MELI) in Latin America, and Sea limited (ticker: SE) in Asia and their effect on cross border commerce. I did a tree map on Global-E few days ago (Included at the end of the article as supplemental material) which show cases it strengths, on how it is making cross border commerce easy. Mercado Libre is huge in South America. It also has national websites catering to specific countries such as mercadolibre.com.pe for Peru and mercadolibre.com.ni for Nicaragua. It has done an excellent job of 'personalizing' the websites to the countries they cater.

One way to look at extent and reach of a website is to look at server traffic and countries of origination to those sites. I obtained data from Cloudflare to see where the visitors to Mercado Libre are coming from. This gives a good indication of the visitors to the site and a proxy of its reach. 

Method: I obtained the domains for Mercado Libre and its country specific website links. Then using this information obtained the website statistics from Cloudflare.  Cloudflare is a web infrastructure and website security company that provides content delivery network and DDoS mitigation services. The data was limited to last 30 days and provided top 10 locations for visitors to the respective sites. I then cross tabulated data for all of the country specific domains to see where are people visiting from on Mercado Libre's website. Given this was a multivariable data, it is represented as network map which shows the connections in entirety. The figure is shown below.

Figure 1: Country of origin of visitors to Mercado Libre's websites

Results

  1. Blue nodes are country specific websites for Mercado Libre, the key for the countries are Argentina (.ar), Bolivia (.bo), Brasil (.br), Chile (.ch), Colombia (.co), Costa Rica (.cr), Dominicana (.do), Ecuador (.ec), Guatemala (.gt), Honduras (.hn), México (.mx), Nicaragua (.ni), Panamá (pa), Paraguay (py), Perú (.pe), Salvador(.sv),Uruguay (.uy) and Venezuela (.ve) (arrow #1)
  2. The location country of the visitors are nodes colored with gradient green to red and sized. Thus the visitors from the country with highest frequency will be represented by largest nodes that are green while those that are not as frquent will by small and red. For example, in the figure Brazil, Argentina and United States are the largest nodes (most visitors, see dotted shape arrow #2) while Japan and HK (e.g. #3 arrow ) are smallest.
  3. The distance of the node to the domains is based on the frequency of visitors, thus if the nodes are closer to the country node, it means that the visitors from that country were most frequent. For example the Chile node is closest to .cl since most visitors to .cl were from Chile (see arrow #4)

Discussion

Following are my personal observations

  1. That most visitors to Mercado Libre's websites are from Brazil and Argentina and respective LATAM countries is expected, what was not expected there was also considerable website traffic from United States,  Europe (Netherlands, France, UK). This tells me that the MELI footprint extends far beyond LATAM and that visitors to the site are coming from outside of South America as well.
  2. There were some interesting findings as well, there we significantly higher number of visitors from Netherlands and France to Mercado Libres Nicaragua, Honduras and Salvador websites.
  3. There were also visitors from Asian countries like Japan, South Korea, Hong Kong albeit is much lower frequency.

This analysis shows that the visitors to Mercado Libre are more than LATAM countries and the digital foot print extends to US, UK, Europe and even Asia. The analysis has some limitation though for example, the look back period is only 30 days, there could be other patterns is the look back period was extended further. Cloudflare's data only allows for a 7 or 30 day look back. The data is limited to only top 10 countries. Visitors from a country may not mean customers, we do not know the intention or the deliberation of the visitors. While it is possible that some one may accidentally end up on their website, the proportion of those would be fairly small.  Additionally, with the advent of usage of VPN services, the origin of visitors could be spoofed but again this may be expected to be a minuscule proportion and no way to get around this. 

Conclusions: Mercado Libre, Inc. is an Argentine company headquartered in Buenos Aires,  that operates online marketplaces dedicated to e-commerce and online auctions, including mercadolibre.com.  The company operates in South America and has has operations in Argentina, Bolivia, Brazil, Chile, Colombia, Costa Rica, Dominican Republic, Mexico, Spain, Ecuador, Guatemala, Honduras, Peru, Panama, Uruguay, and Venezuela. Thought its operations are seemigly limited to South America, its digital foot print extends well beyond its borders.

Disclaimer: I own shares of Mercado Libre (MELI) and am invested in the company. The data was obtained from public sources.

Addendum:

Figure 2. Global-E, GLBE a cross boundary commerce platform


Saturday, September 18, 2021

Lemonade (LMND), a semantic analysis of earnings: time to buy?

or Why I am not investing in Lemonade - LMND (...yet)

Early in August Lemonade insurance company announced their earning and quarterly updates. The stock did not farewell, creating a potential buy opportunity. This was also discussed quite a bit on the various internet fora and there were many proponents of the stock as well as those who felt that perhaps it was not the right time. This piqued my interest in LMND since it is a finance-tech (fintech) insurance company. Lemonade Inc. offers a number of products including renters' insurance, homeowners' insurance, pet insurance and term life insurance in the United States. They also operate in limited areas of Europe such as Germany, the Netherlands, and France. They have a predominantly young demographic (approx 65-70%) and catchy ads to target to their target population. 

This encouraged me to dig deeper in to their earnings, operations and fundamentals with 'semantic network analysis'. You may perhaps know from my other articles on the site, I believe this method is unique in that it allows to seek hidden patterns or those connections that are not immediately revealed. 

The rationale for doing something like this is that ALL text has a linear structure (which is top-down, left to right etc) which  is the most common way of conveying information. However, in this linear flow, certain connections can be missed. Unsupervised Concept network analysis takes concepts in the text and breaks them into parts, which are then connected by common linkages. It is process intensive but is highly informational. This nonlinear text visualization of concept linkages allows for hidden patterns to be revealed, read between lines. 

With that brief intro, let me walk you through the process of my analysis of Lemonade's reports. The earnings came out on August 4th, 2021, right after this came out, I generated my unsupervised semantic network to analyze if it was a good opportunity to invest in LMND. This network model is shows in figure 1.

Figure 1: An unsupervised semantic text network analysis of Lemonade Co. earnings
Each node above, represents a tangible concept and entity and it is linked by edges (lines) which connect the related nodes.

  • Light blue nodes: pertain to discussion on Lemonade car, their car insurance product
  • Green nodes: pertain to their financial situation and their arrangement with reinsurance markets
  • Yellow nodes: are their existing products (home, pet etc)
  • Pink nodes: pertain to their progress and expansion plans
  • Purple nodes: pertain to their ESG efforts

Then using a computational algorithm (force-directed layout) to space them out, linked nodes are pulled closer while those that are not related are pushed apart. This is how patterns and connections emerge (figure 1).

FOUR broad themes emerge

1) Reinsurance drag: The is a big factor weighing down the business and that is the their necessary partnership with reinsurance industry. They are contracted to cede 75% of the premium they obtain from customers that obtain insurance through Lemonade. This is going to be a big drag until 2023, when they will renegotiate the terms of this contract. They are showing some improvement in reducing this percentage but it will continue to be a drag. Also there is 'new business penalty' which means as they expand into new lines of business, this penalty will tack on and eat into their profit margin. This was huge flag for me. A turnaround for me would be to see this at much lower percentage (ideally zero) to renegotiate after 2023 and see what terms are offered. Moreover, the location of this cluster of nodes right between Lemonade car (light blue) cluster and other products (yellow nodes), tell me of the profound impact this has on their operations.

2) Verticals need better performance and integration: Their products are mature and work HOWEVER, the performance across the board is lumpy. Some products (yellow nodes in graph) are floundering like life and renters while others are doing better (pet). A turnaround factor for me if, in next few quarters, we see company firing on all cylinders for ALL of their products.

3) Lemonade car still has to go live: there are significant goals that need to be met before their car insurance product is ready. It is revolutionary no doubt - where car insurance is going to based of telematics data and AI etc. So far they do not have regulatory approvals and did not provide launch dates. A turn around for me on this would be is a) they get regulatory approvals and b) they launch it.

4) The ESG nodes and the expansion nodes are sparse: This part of the network graph was anemic, at least as far as their discussion goes. I would like to see a much more robust patterning here.

The stock has fallen another 10-12% since and as of today the chart looks like this (figure 2, below)

Figure 2: Technical set up for traders (image courtesy: Stockcharts.com)
 

A technical view of the stock shows a divergence between stock price and RSI as well as MACD (image from www.stockcharts.com) which may suggest they a small price improvement is possible. This may be okay for stock traders who want to try and scalp some profits. However, the underlying fundamental story has not changed for me and so as a long term investor, I have NOT entered into a long position yet.

Conclusion: Based on my semantic analysis I decided to not invest in Lemonade and wait till there are improvements in certain key issues.

Friday, September 17, 2021

Zoom Video Q2 2022 post earnings breakdown, a semantic network analysis

Zoom Video: With it being down 18% in my portfolio it is time to question my beliefs and decide whether to add, hold, pare or get out. The following post is a step-by-step walk through of my process, reasons and conclusions. Brace yourself, its a long one. TLDR at bottom. 

Lets begin,

On Zoom developments:

Figure 1: Zoom Apps discussion

Zoom apps section of Zoom has nicely thought out plan with an internal and external work force (Start ups, zoom apps fund). I think this will continue to crank out developments given its set up. The network model is shown in the figure (Fig. 1). CEO called this "internal innovation engine".

Figure 2: Zoom events discussion

Zoom events is presented as a step above webinars and meeting with its USP being a solution for mass reach to host and produce events. This is not experimental, but a fully functioning product which the company has tested on its own event 'Zoomtopia'. See figure 2 above.


Figure 3: Zoom 'wins' this quarter

In the sales (Figure 3), they made some good sales with both new large customers as well as up-sells to prior customer. Main emergent theme, I got was 'Zoom phone' is being offered as 'Chef's special' and is likely being pushed hard. If this is the case, then zoom phone numbers will improve QoQ and people will start seeing traction in addition to zoom meetings. More interestingly is the partnership with Telkomsel which is Indonesia's largest cellular/internet Telecommunications provider.

Figure 4: Zoom has identified a clear need that enterprises have

The CEO has nicely outlined what they see as their target audience. It is the offices, organizations they are going after and filling the enterprise need for a digital platform that does communication (Figure 4)

Chief Finance Officer's section

1. Enterprise customers spending more than $1 million in ARR up by 77% year over year
2. A lot of Zoom phone numbers - see the comment above on pushing this product.
    - number of customers spending more than $100,000 in ARR on Zoom Phone by 241% year over year.
    - 2 MM Zoom Phone seats, eight months after reaching first million.
    - Eight Zoom Phone customers with more than 10,000 seats in the first half of FY '22, to a total of 26.
    - largest Zoom Phone deal to date twice in the same day.

Cautionary comment (I): customers return to more thoughtful, measured buying patterns. While revenue, profitability, and cash flow were strong in the second quarter and the first half, other metrics have begun to normalize, especially when compared to the unprecedented year-over-year comps.

3. total revenue grew 54% year over year to $1.02 billion,
4. Strength in direct and channel businesses, which grew at twice the rate of online business.
5. Zoom Phone, Zoom Rooms, and Asia PAC growth also accelerated in the quarter
6. healthy mix between new (74%) and existing customers (26%) of incremental revenue.
7. Approximately 504,900 customers >10 employees, up 36% year over year and representing 64% of revenue.
8. Net dollar expansion rate for above group exceeded 130% for the 13th consecutive quarter as existing customers increased their spend
9. customers < 10 employees down to 36% of revenue (from 38% highest)

Cautionary comments (II): Small and medium sized businesses and consumers < 10 employees are expected to continue to decline as a percentage of revenue.

10. Regional news: Americas revenue grew 50% year over year. Combined APAC and EMEA revenue grew 62% year over year to be approximately 33% of revenue, up from 31% a year ago. significant investments in Asia Pacific, our direct sales team drove several strong wins in the enterprise segment (See NEC).'

Cautionary comment (III)
: headwinds in EMEA (Europe, ME and Africa) declines in the online segment.

On Their Spend :

1. Research and development expense grew by 89% year over year – needed for innovation. At present 5% of rev target is 8% (See below section)
2. Sales and marketing expense grew by 72% year over year to $211 million - plan to increase investment in global sales capacity, as well as digital marketing and events,
3. G&A expense in the quarter grew by 73% to scale and invest in systems, automation, and compliance to meet our new scale.
4. Remaining performance obligation (RPO) totaled approximately $2.3 billion, (up 66%) of which 69% will be collected over 12 months. Q1 represents largest renewal quarter.

Cautionary comments(IV): Zoom expects that front-weighted seasonality will persist and potentially become even more pronounced given the scale of user base. They expect total deferred revenue and RPO to be modestly down from Q2 to Q3. RPO serves as a proxy for future revenue, the RPO growth rate provides a leading indicator of growth but Zoom indicates that may not be the best measure to gauge one aspect of their growth.

My take

The market has reacted appropriately to the cautionary comments provided with gap down in the price of ZM stock after earnings. However, I believe this setback is transient and the business will get over the headwinds and declines noted. Based on the goal identified by CEO, they are going to target enterprises hence, they may not be planning to target the small <10 employees companies anyways. RPO is expected to be down from Q2 to Q3, due to seasonality..look at this as not QoQ but a Year over years comparison. 

Q and A highlights

"headwinds in the online segment (zoom meetings) of our business but continued strength in the upmarket enterprise in both Meetings and Phone."

General: The tone and sentiment of the earnings call was mixed which was aptly correspond with the drop in share price after the earnings conference. That being said lets dig in, I personally do not want to focus exclusively on online segment to decide Zoom's worth. The reduction in usage here, is expected, people are not "zooming" as much since they are going out and doing things in person. Also, individual users, smaller users are sort of the 'side shuffle'. This reduction in online segment is also what management thinks is the headwind for the Europe, middle east and Africa. 

The CEO has made it clear that zoom is targeting the enterprise segment which is doing very well. Areas of growth are Zoom phone (presently adding about 500K seats every Quarter), Zoom corporate licenses and Zoom Rooms all which are showing good numbers in growth. 

Zoom online had a different motivation when people jumped in on it, it was "desperation", but now with vaccine and better understanding of the situation, people can be deliberate in their purchases. The latter is whats happening to Zoom Phone, the fact that it is showing improvement, is telling  me, that the decision to increase corporate licenses and buying more seats on phone are deliberate decisions and not desperate actions. Deliberate actions provide a stable revenue, as opposed to volatility of desperate actions.

On Five9 acquisition: Current users (including enterprise customers) per zoom want to migrate from on-premise to the cloud. Having an integrated phone and contact center solution (Zoom + Five9) would be attractive to companies. This would be new revenue stream and grow Zoom business. Based on this assessment, CEO believes it is appropriate to double down on the cloud as the contact center of those.

On monetization of free users: Schools through K-12 will not be monetized. Kudos on firm moral compass and karmic gains on goodwill. Also, this is a long term investment, kids who use and are familiar with zoom tech are going to be adults who will use zoom tech. bravo! I also like the fact, they the leadership is acutely aware of where and when to monetize, for example, they felt that further monetization of online users (mom and pop store, smaller companies individual users) may not be the sustainable strategy. Hybrid adoption in EMEA is lagging APAC which is lagging US (my impression) when these pick up, these will be stimulants for higher growth.

On vision to sustain growth:
"Yesterday":    Zoom videoconferencing
"Today":         Zoom Videoconferencing PLUS Zoom Phone
"Tomorrow":     Zoom Videoconferencing PLUS Zoom phone PLUS Zoom platform/Full suite

On predicting user trajectory: One analyst asked when the zoom online (smaller users) will trough out and growth of enterprise segment will dictate the discussion. This was an unfair question since boom in online users was pandemic driven, and attempting to answer this question is akin to predicting future course of pandemic.

On relationship of zoom phone and zoom meeting numbers: Analyst at Piper-Sandler asked a good question IMO. They wanted to know if zoom phone is leading to a greater number of seats at existing customer. The CEO's answer was not as clear on this one. It may seem that one year ago, Zoom did not expect it would up sell phones to existing base in amount that it did. They were anticipating new customers to bundle video and voice through phone. But it seems that more customers are going to deploy video first and then deploy Phone.

On competition from other services: Future work will be hybrid work and mainstream. Embracing hybrid work by employees, students, WFH, will require a solution. Per Zoom, a 'good enough' solution will not do well (which Zoom claims are other services). Zoom claims it is best-of-breed with better IT support and productivity tools  (which others do not have same level of). 

On expenses: Zoom was not able to hire and invest in proportion to revenue growth. They are under-invested in our R&D (5%), with goal of 8%. Continue to spend on marketing.  G&A is in range of where it needs to be. Cost of good sold (COGS) will reduce as services move from public cloud to Zoom data centers. As K-12 schools go back to campuses, expect to see  improvement in our gross margins.

On Zoom events: This was a redesign of OnZoom to meet the demand of enterprises for corporate events. Consumers (like online fitness or cooking class) are expected to catch on.

Approximately a 1/3 of the analysts were focused on the online meetings, and small users segment which may have given an overall disappointing tone to the discussion. There are however quite promising pieces of information which are reassuring.

Verdict: I will hold on to my Zoom shares, as of time of this note they were down ~18%, if they drop more, I will add to lower the cost basis and to keep the draw down around 20%.

Popular Posts